What is the market overview of the Process Oil Market?
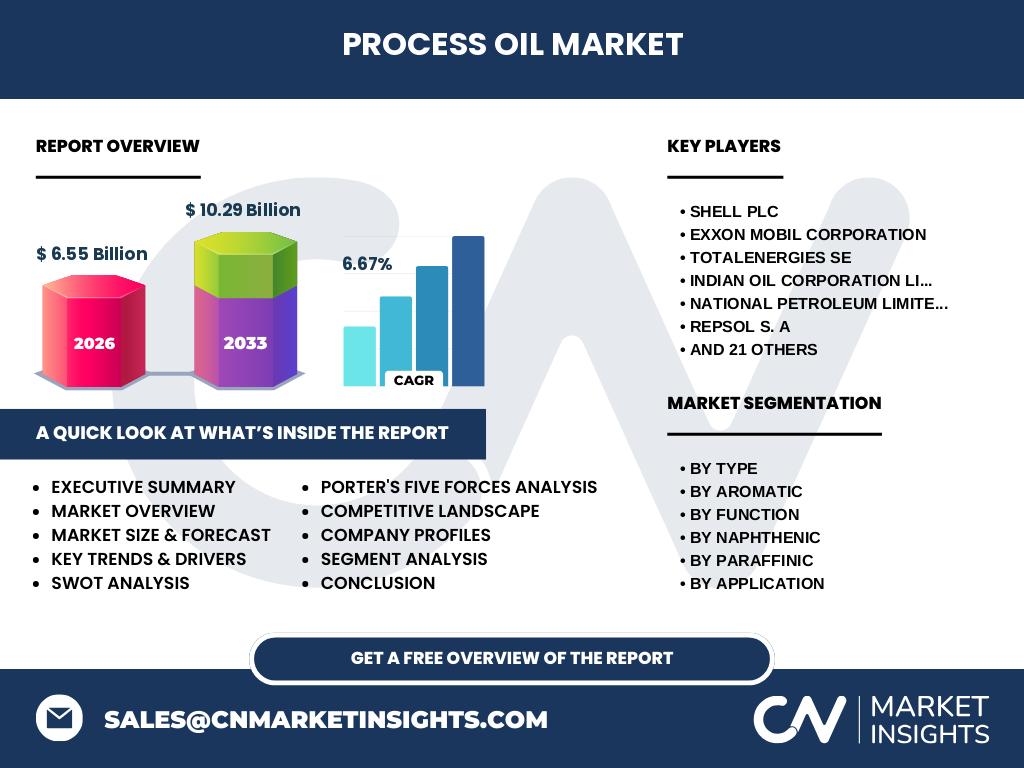
Our analysis indicates that the Process Oil Market is valued at $6.55 Billion in 2026. This sector encompasses specialized petroleum-derived fluids utilized as vital compounding ingredients across rubber compounding, adhesives, and polymer manufacturing, anchoring global industrial output.
Key market drivers, restraints, challenges, and opportunities shaping Process Oil Market
Growth is propelled by expanding tire and automotive sectors, while strict REACH regulations restricting aromatic content constrain traditional grades. Opportunities abound for non-carcinogenic innovations developed by industry pioneers like Nynas AB and Shell plc.
Emerging trends and growth patterns in Process Oil Market
The industry is witnessing an aggressive pivot toward treated distillates. Environmental compliance forces producers to adopt severe hydrotreating technologies, favoring specialized portfolios from Exxon Mobil Corporation and TotalEnergies SE.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions and automotive shutdowns caused a temporary contraction in 2020. Recovery has been robust, driven by localized chemical manufacturing resurgence and aggressive inventory restocking across major Asian and European processing hubs.
Competitive landscape and strategic dynamics
Market concentration remains moderate to high, dominated by integrated energy majors. Competitors like Chevron Corporation and Saudi Aramco leverage feedstock integration, whereas specialty blenders like Calumet Specialty Products Partners L.P. compete via customized customer formulations.
Executive summary of the Process Oil Market
Our research forecasts the Process Oil Market to surge from $6.55 Billion in 2026 to $10.29 Billion by 2033 at a 6.67% CAGR. Success requires navigating stringent environmental mandates while expanding eco-friendly grades.
Market forecast from 2027 to 2033
Driven by rising industrialization and elastomer demand, the market is projected to expand from $6.55 Billion to $10.29 Billion, achieving a steady 6.67% CAGR throughout the forecast window as specialty formulations replace commodity oils.
Segmentation analysis of the Process Oil Market
Our segmentation breaks down by type into Naphthenic, Paraffinic, Non-Carcinogenic, and Aromatic. Functions include extender oil, plasticizer, and solvent, while applications span rubber processing, adhesives, and paints, each serving distinct industrial mandates.
Regional market analysis and geographic distribution
Asia-Pacific dominates consumption due to massive tire manufacturing hubs in China and India. North America and Europe focus heavily on stringent environmental compliance, accelerating adoption of non-carcinogenic variants supplied by regional refiners like HF Sinclair Corporation.
In-depth regional review
Emerging economies in Southeast Asia show the highest elasticity, fueled by automotive investments. Meanwhile, mature European markets enforce strict polycyclic aromatic hydrocarbon limits, compelling local manufacturers to partner with specialists like H&R GROUP.
Company profiles and strategic positioning
Global leaders such as Idemitsu Kosan Co. Ltd. and Indian Oil Corporation Limited deploy advanced hydrogenation units. Regional players like Apar Industries Ltd. and Gandhar Group capture market share through tailored customer service and agile supply chains.
Porter's Five Forces analysis
Bargaining power of suppliers is moderate due to crude oil dependency. Threat of substitutes remains low given the irreplaceable chemical nature of process oils in rubber compounding, though competitive rivalry among top-tier refiners is intense.
SWOT analysis of the industry
Strengths lie in established petrochemical infrastructure and vital end-use demand. Weaknesses involve raw material price volatility. Opportunities center on eco-friendly plasticizers, while threats stem from aggressive regulatory crackdowns on toxic aromatic fractions.
Value chain analysis from raw materials to end-users
The value chain starts with crude oil extraction by firms like PJSC Rosneft Oil Company, moving through vacuum distillation and solvent extraction by refiners, down to specialized formulation, and concluding with industrial end-users in rubber and polymer sectors.
Investment insights and high-potential areas
Investors should target greenfield hydrotreating facilities capable of producing low-PCA naphthenic and non-carcinogenic grades. Strategic partnerships with regional blenders in high-growth developing markets offer superior risk-adjusted returns over traditional commodity refining.
Conclusion and key takeaways
Reaching $10.29 Billion by 2033 at a 6.67% CAGR, the Process Oil Market rewards sustainability and technological adaptation. Regulatory compliance is no longer optional; it is the primary engine of competitive differentiation.
Research methodology for baseline estimates
Our triangulation methodology combines exhaustive primary interviews with refinery executives, import-export customs registries, and secondary macroeconomic indicators from energy agencies to validate market sizing and segment growth trajectories.
Scope of the report and coverage parameters
This report evaluates global trends from 2027 to 2033, analyzing volumetric demand and revenue across all major types and applications. Exclusions involve unregistered localized grey-market blenders operating outside formal regulatory tracking.
Recent developments and strategic moves
Industry leaders are actively reshaping portfolios; for instance, PT Pertamina and Thai Oil Public Company Limited have invested in upgraded hydroprocessing units to meet shifting environmental standards, while major players pursue regional distribution joint ventures.